Your tenants cover most or all of the mortgage
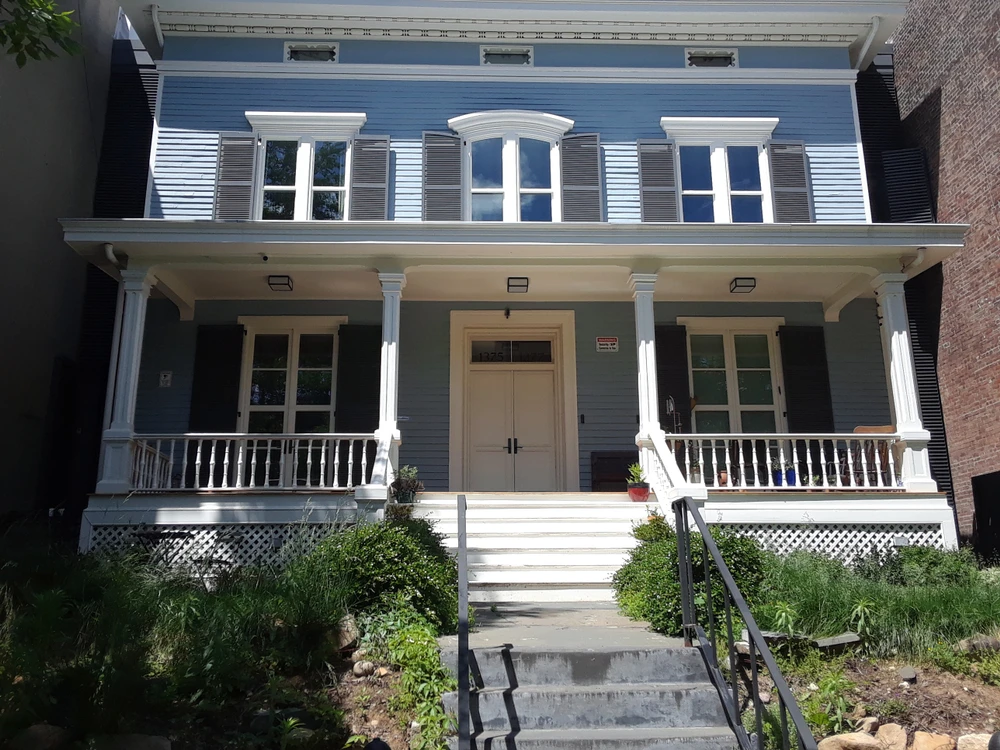
House Hacking a Plex: How Beginners Build Wealth Faster

I lost everything in 2008. Fifty million dollars, gone. When I talk to people starting out now, the thing I push hardest is not a strategy that makes the most money. It is the one where a beginner’s mistakes do not end them. House hacking a plex is that strategy.
You buy a two to four unit building, live in one unit, and rent the others. Your tenants cover most or all of the mortgage while you learn to be an operator on a property small enough that getting it wrong is survivable.
The Short Answer
House hacking means buying a two to four unit property, living in one unit, and renting the rest. Because you occupy it, you qualify for owner occupant financing with down payments as low as 3.5 percent on an FHA loan rather than the 20 to 25 percent a pure investment property requires. Your tenants pay down your mortgage, you build equity on all the units, and you learn screening, maintenance and rent collection on a property small enough to survive your early mistakes.
The reason I call it the best possible start is not the returns. Plenty of strategies beat it on paper. It is that house hacking gives you leverage, cash flow, equity and operating experience at the same time, on one property, using money you were going to spend on housing anyway.
Is House Hacking Right for You?
Be honest on these before you start looking at listings.
- You are willing to live next door to your tenants, and to be the person they call about a leak.
- You can stay in the property at least a year, which owner occupant loans require.
- You have reserves beyond the down payment. A vacancy or a water heater arrives eventually.
- You are comfortable screening tenants properly, including saying no to someone you like.
- Your market actually has two to four unit properties. Some do not.
- You want to own more property later, not just lower this month’s housing cost.
That last one matters more than people expect. House hacking works as a first step. Treated as a destination, it is just a cheaper place to live.
The House Hack Stack
Here is what makes this different from every other entry point. Most first moves in real estate do one thing for you. This does five at once.
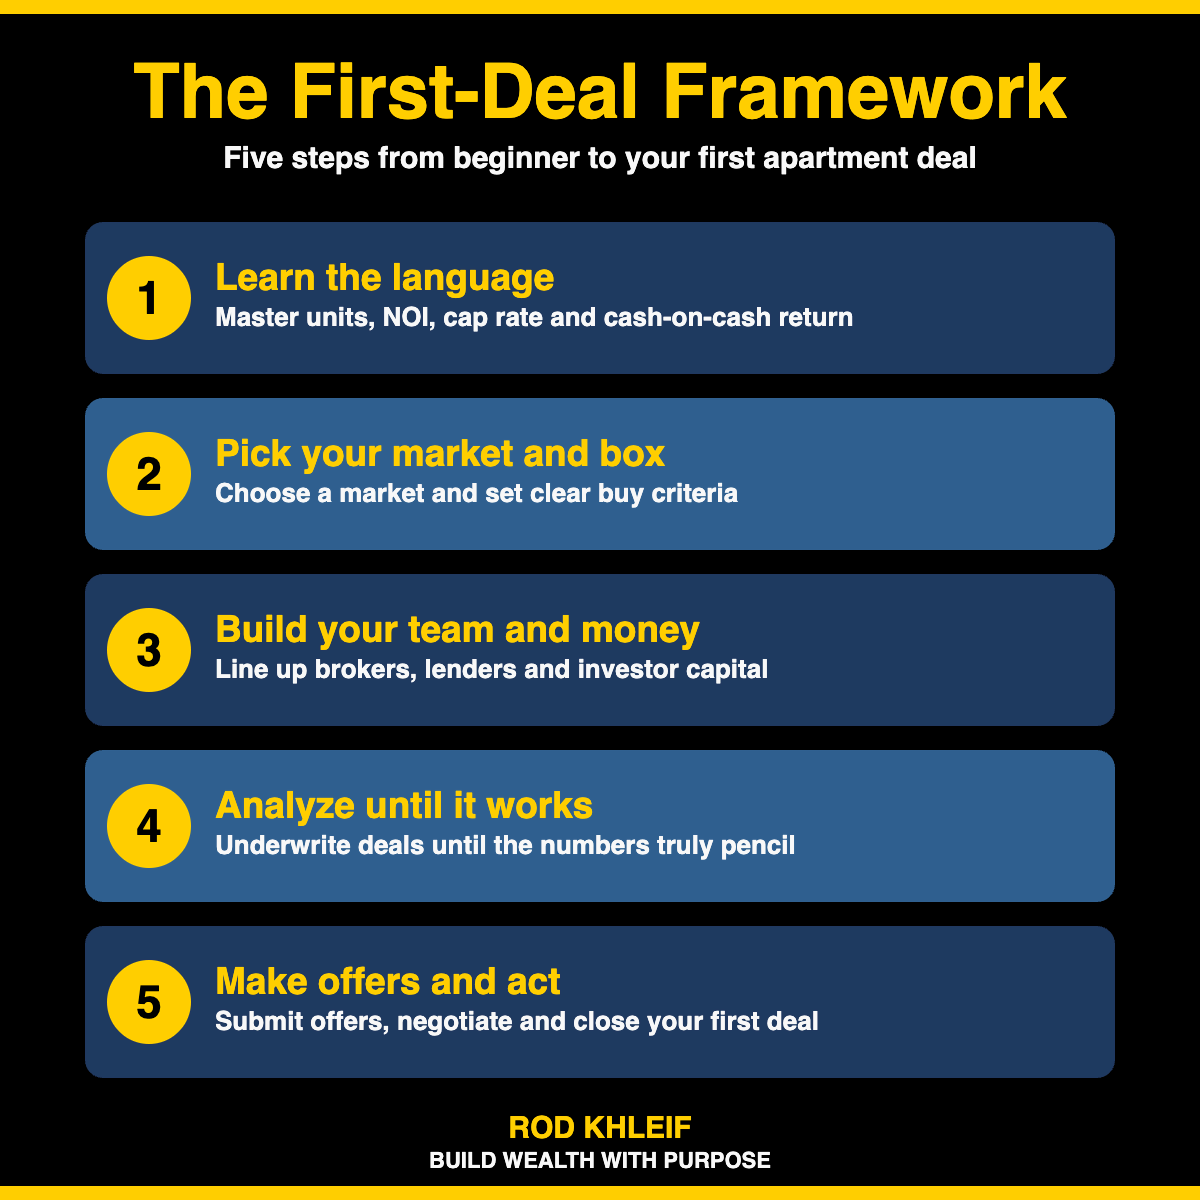
What Is Multifamily Investing?
Multifamily investing means buying residential properties with two or more units. These include apartment buildings, duplexes, triplexes, and larger complexes. The goal is to earn rental income and build long-term wealth.
Unlike single-family homes (which have one tenant and one rent check), a multifamily property generates multiple streams of income from a single acquisition. That’s the core appeal: you buy once and collect from many.
Types of Multifamily Properties
| Property Type | Units | Key Characteristics |
| Duplex, Triplex, Fourplex | 2 to 4 units | Residential financing available. A great starter property. |
| Small Apartment Buildings | 5 to 20 units | Crosses into commercial lending territory. |
| Mid-Size Apartments | 20 to 100 units | More economies of scale. Requires professional management. |
| Large Apartment Complexes | 100+ units | Institutional grade. Typically syndicated. |
Why Does Unit Count Matter?
One critical line every investor needs to understand: properties with 4 or fewer units qualify for residential mortgages (with favorable rates and low down payments). Properties with 5+ units require commercial loans, but they also unlock far greater cash flow potential.
Rod Khleif often says that moving from a 4-unit to a 5-unit property is a big mindset shift. You stop thinking like a landlord. You start thinking like a business owner.
Multifamily investing is not just a real estate strategy. It’s a way to create what Rod calls “lifetime cash flow.”This is recurring, passive income that replaces your job income.It also funds your ideal life.
Get a Free Multifamily Loan Quote
Access Non-Recourse, 10+ Year Fixed, 30-Year Amortization
Why Multifamily Beats Single-Family
This might be the most important section of this entire guide. The single-family vs. multifamily debate isn’t close. For investors who want to scale, build lasting wealth, and eventually replace their income, multifamily wins every time. Here’s why.
Multiple Income Streams From One Acquisition
With a single-family rental, losing your one tenant means $0 in income. With a 10-unit apartment building, one vacancy is a 10% loss, manageable. The more units, the more stable and predictable your cash flow becomes.
Economies of Scale
One roof. One insurance policy. One property management relationship. One set of maintenance systems. Managing 10 units in one building is exponentially more efficient than managing 10 single-family homes scattered across a city.
Faster Portfolio Growth
Buying one 20-unit building moves your portfolio forward faster than acquiring 20 individual houses. The time, legal costs, inspections, and financing for a single acquisition apply regardless of how many doors are included.
Commercial Valuation Based on Income
Single-family homes are valued by comparable sales, your neighbors’ home values control yours. Multifamily properties (5+ units) are valued based on Net Operating Income (NOI) and cap rates. That means you can directly force appreciation by raising rents and cutting expenses, regardless of the market.
Easier to Finance at Scale
Banks love apartment buildings. Why? Because a diversified rental income from multiple tenants is a safer bet than a single tenant in a house. Many investors are surprised to find that getting approved for a $3M apartment building can be easier than a $300K single-family loan.
| Factor | Single-Family | Multifamily |
| Vacancy risk | Lose 100% of income when the unit is empty | One vacancy is a small share of total income |
| Valuation method | Based on comparable sales | Based on the income (NOI) you control |
| Scale speed | One deal equals one unit | One deal equals many units |
| Management efficiency | Low | High |
| Forced appreciation | Very limited | Substantial through higher NOI |
| Bank perception | Individual borrower | Business operator |
How to Analyze a Multifamily Deal
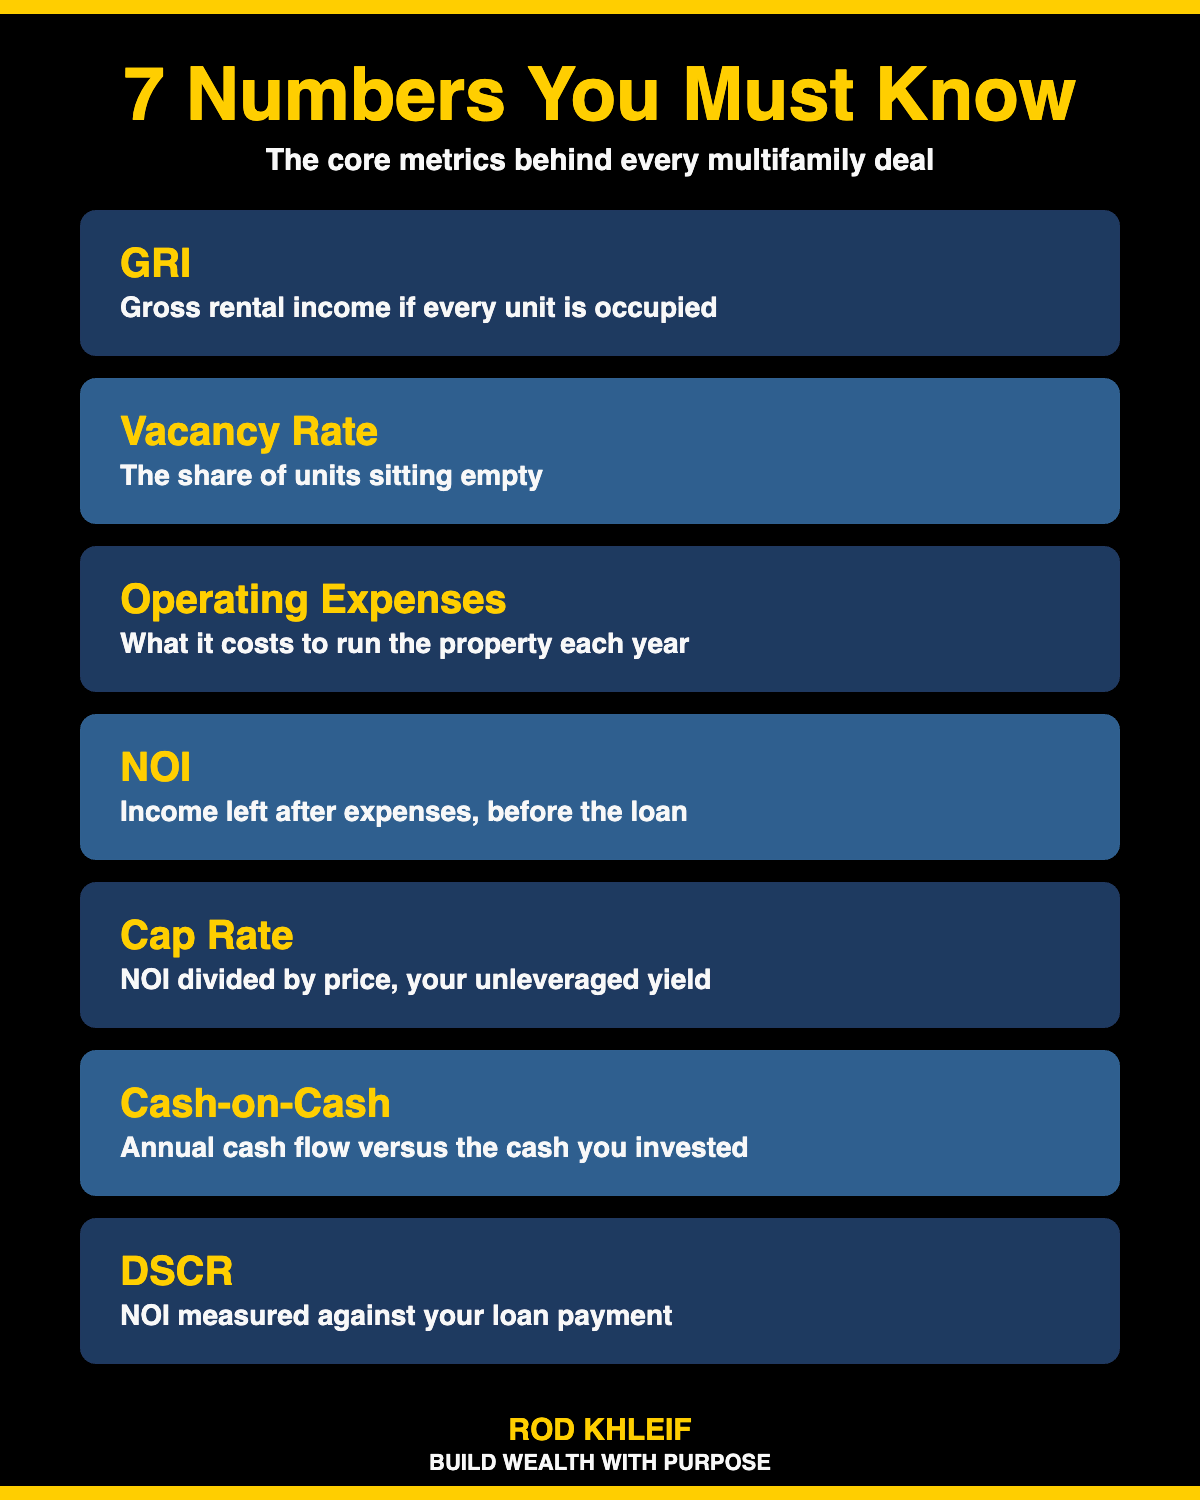
Deal analysis is the skill that separates investors who build wealth from those who lose money. The good news: once you learn the framework, it becomes second nature. Here are the core metrics every multifamily beginner needs to master.
Gross Rental Income (GRI)
Start with total potential rent if every unit were occupied at market rate. This is your ceiling number before any deductions.
Vacancy Rate
Typically assumed at 5–10% depending on the market. Subtract this from GRI to get Effective Gross Income (EGI). Never underwrite a deal at 0% vacancy, that’s wishful thinking, not analysis.
Operating Expenses
Common operating expenses include property taxes, insurance, property management fees (typically 8–10% of rent), maintenance and repairs, utilities (if owner-paid), landscaping, and reserves. A common rule of thumb: expenses run 35–50% of gross income for most apartment buildings.
Net Operating Income (NOI)
NOI = Effective Gross Income − Operating Expenses.
This is the single most important number in multifamily analysis. It tells you how much the property earns before debt service.
Cap Rate
Cap Rate = NOI ÷ Purchase Price. The cap rate tells you what return you’d get if you bought the property all-cash. Higher cap rate = higher yield. Markets with more risk or less demand typically have higher cap rates.
Cash-on-Cash Return
Cash-on-Cash = Annual Cash Flow ÷ Total Cash Invested. This is the metric that actually tells you how your invested dollars are performing. Many experienced investors target 8–12%+ cash-on-cash returns.
Debt Service Coverage Ratio (DSCR)
DSCR = NOI ÷ Annual Debt Service. Lenders require a DSCR of at least 1.20–1.25, meaning the property generates 20–25% more income than it costs to service the debt. Higher is better.
| Quick Deal Analysis Example
10-unit building | $1,500/unit/month market rent GRI: $180,000/year Less 7% vacancy: $167,400 Less operating expenses (42%): $70,308 NOI: $97,092 Purchase price: $1,100,000 → Cap Rate: 8.8% Annual debt service (30yr/6.5%): $69,500 Annual cash flow: $27,592 Down payment (25%): $275,000 → Cash-on-Cash: 10.0% |
How to Finance a Multifamily Property
matically.
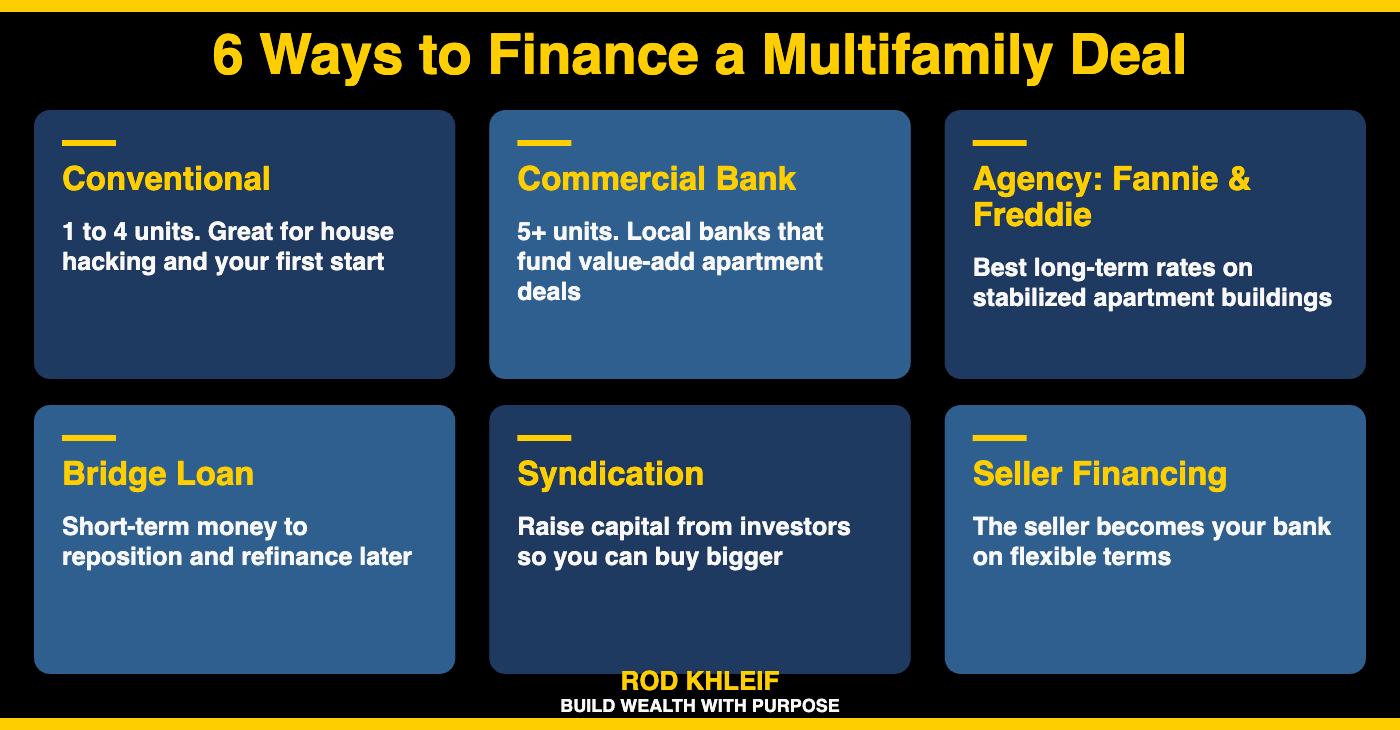
One of the biggest myths beginners believe is that you need a lot of money to get into multifamily. The reality is there are multiple financing paths and some require very little of your own capital.
Conventional / Residential Loans (1-4 Units)
For duplexes, triplexes, and fourplexes, you can use a standard residential mortgage. If you plan to live in one of the units (house hacking), FHA loans allow down payments as low as 3.5%. This is often the best starting point for new investors.
Commercial Bank Loans (5+ Units)
Once you cross the 5-unit threshold, you need a commercial loan. These are typically based on the property’s income (DSCR), not just your personal income. Down payments are usually 20–30%, and terms are often 5–7 year fixed rates with 20–25 year amortization.
Agency Loans: Fannie Mae & Freddie Mac
For larger stabilized properties, agency loans offer some of the most favorable terms available, low rates, long amortization, and non-recourse structures. These require the property to meet specific occupancy thresholds (usually 90%+).
Bridge Loans
For value-add deals that aren’t yet stabilized, bridge loans provide short-term financing (typically 12–36 months) while you renovate and lease up the property. Rates are higher, but they allow you to acquire deals that traditional lenders won’t touch.
Syndication: Using Other People’s Money
This is where multifamily really accelerates. Syndication allows you to pool capital from multiple investors (limited partners) to buy larger deals than you could alone. You act as the General Partner (GP): you find the deal, manage the execution, and earn a share of profits. LPs provide the equity.
Seller Financing
Some motivated sellers will carry the note themselves, acting as your bank. This can eliminate the need for traditional financing entirely and is especially useful in today’s higher-rate environment.
How to Find Multifamily Deals
Knowing how to analyze and finance deals is useless if you can’t find good ones in the first place. Deal flow is the lifeblood of any multifamily investor’s business and the best investors build multiple channels simultaneously.
Commercial Real Estate Brokers
The most common source for 5+ unit properties. Build relationships with brokers who specialize in multifamily in your target market. Be direct about your buy box (size, price range, return requirements) and follow up consistently. The best deals often go to investors who have already established trust.
Direct-to-Owner Outreach
Many apartment building owners are not actively selling but would consider the right offer. Direct mail, cold calling, and driving for dollars (identifying properties in person) are all proven tactics. The owner of a tired, poorly maintained building is often a motivated seller.
Loopnet, CoStar & Crexi
These are the primary online marketplaces for commercial properties. LoopNet has free listings; CoStar (which owns LoopNet) is a professional-grade paid platform used by brokers. Crexi is a newer platform with a growing multifamily inventory.
Networking and Word-of-Mouth
Real estate is a relationship business. Attending local and national multifamily events, joining investor communities, and building relationships with property managers, lenders, and attorneys will surface off-market opportunities that never make it to a listing platform.
Pocket Listings and Off-Market Deals
Many of the best deals are never publicly listed. Brokers will often share pocket listings — properties they represent before officially listing — with investors they trust and know can close. Position yourself as a credible, prepared buyer and these opportunities will find you.
How to Manage a Multifamily Property
Property management is where deals succeed or fail. Excellent management protects your cash flow, extends the property’s life, and keeps residents happy and long-term. Poor management erodes NOI, triggers vacancies, and destroys returns.
Self-Management vs. Third-Party Management
| Factor | Self-Management | Third-Party Management |
| Cost | Free, but it costs your time | Roughly 5 to 10% of collected rent |
| Best for | Local investors with small properties | Scaling investors and larger properties |
| Scalability | Limited and time intensive | High |
| Control | Maximum | Less day to day control |
| Learning curve | High | Low |
For most investors scaling past 20–30 units, professional management is the right move. The 8–10% management fee buys you time — and time is the real leverage in this business.
What a Property Manager Does
- Tenant screening (credit, background, income verification)
- Rent collection and handling late payments
- Maintenance coordination and vendor management
- Lease renewals and rent increase negotiations
- Monthly financial reporting (income statements, variance reports)
- Handling evictions if necessary
Key Performance Metrics to Track
- Occupancy Rate — Target 93%+
- Average Days Vacant — Each vacant day is lost revenue
- Maintenance Cost per Unit — Track and benchmark annually
- Rent-to-Market Ratio — Are you getting market rent or below?
- Net Operating Income — Review monthly against your pro forma
Value-Add Property Management
Many beginner investors acquire properties with below-market rents. As existing leases expire, you raise rents toward market rate — each dollar of additional annual NOI adds $12–16 to the property’s value at a 6–8% cap rate. This is one of the most powerful wealth-building levers in multifamily.
Common Beginner Mistakes to Avoid
Every experienced multifamily investor has made costly mistakes. The good news: most of them are entirely avoidable with the right knowledge and guidance upfront. Here are the most common errors beginners make:
-
Underestimating expenses. Most beginners use overly optimistic expense ratios when running pro formas. Build in a realistic 40–50% expense ratio and always include a capital expenditure reserve.
-
Skipping proper due diligence. A full property inspection, rent roll analysis, operating statement review, and local market analysis are non-negotiable before making an offer.
-
Over-leveraging on the first deal. Putting too little down or relying on bridge debt with no clear exit strategy can lead to disaster if the market shifts.
-
Choosing the wrong market. Not all markets are created equal. Research population growth, job growth, rent trends, and landlord-tenant laws before selecting your target market.
-
Managing without systems. Trying to handle everything manually as your portfolio grows leads to burnout and costly errors. Build management systems and software from day one.
-
Going it alone. The investors who scale fastest almost always have a mentor, a network, or a community around them. Isolated investors make more costly mistakes and move more slowly.
Investing While Working Full-Time
One of the most common questions Rod hears: “Can I really build a multifamily portfolio while I have a full-time job?” The answer is an emphatic yes, and many of the most successful Warrior Program students did exactly that before replacing their income.
The Time Reality
Actively acquiring multifamily properties does require time, for deal analysis, broker relationships, due diligence, and financing. But it doesn’t require 40 hours a week. Most investors who are getting started spend 5-15 hours per week on their business, primarily in the evenings and weekends.
The W-2 Advantage
Having a steady income while building your portfolio is actually a huge advantage. Banks love the income stability that comes with W-2 employment, especially for your first few deals. Your day job income makes you a more attractive borrower and lets you weather early challenges.
How to Structure Your Time
- Mornings (6-7am): Deal analysis and market research
- Lunches: Broker and networking calls
- Evenings (1-2 hours): Underwriting, education, community engagement
- Weekends: Property tours, due diligence trips, events
Multifamily Investing Glossary
Get fluent in the language of apartment investing. Knowing these terms makes you a credible buyer with brokers, lenders, and sellers from day one.
| Term | Definition |
| Cap Rate | Measures unleveraged yield. NOI divided by purchase price. Example: an 8% cap on a $1M property means $80K of NOI. |
| NOI (Net Operating Income) | Revenue minus operating expenses, before debt. The core number behind all commercial valuation. |
| DSCR (Debt Service Coverage Ratio) | NOI divided by your annual debt payment. Lenders typically require 1.20 or higher. |
| Cash-on-Cash Return | Annual cash flow divided by the cash you invested. Measures your actual cash return. |
| GRM (Gross Rent Multiplier) | Price divided by annual gross rent. A quick comparison metric. |
| Value-Add | A property with upside through rent increases or improvements. A common acquisition strategy. |
| Pro Forma | A forward-looking income and expense model. The projected financials for a deal. |
| LTV (Loan-to-Value) | Loan amount divided by property value. 80% LTV means a 20% down payment. |
| Bridge Loan | Short-term financing for transitional properties, usually 12 to 36 months. |
| GP / LP | General Partner (operator) and Limited Partner (passive investor). The standard syndication structure. |
| Preferred Return | LP investors get paid first, up to a threshold. Typically 6 to 8%. |
| Waterfall | How profits are split after the preferred return. Commonly 70/30 or 80/20 GP/LP. |
| CapEx (Capital Expenditure) | Major property improvements such as roof, HVAC, and plumbing. |
| Rent Roll | A list of all units, tenants, rents, and lease terms. A critical due diligence document. |
| Vacancy Rate | The percentage of units not occupied at a given time. Underwrite at 5 to 10%. |
| Operating Expenses | All costs to run the property except debt: taxes, insurance, management, and maintenance. |
| Class A / B / C | Property quality grades by age, condition, and location. C offers the most value-add potential. |
| 1031 Exchange | A tax-deferred property swap that defers capital gains. A powerful wealth-building tool. |
| NNN Lease | The tenant pays taxes, insurance, and maintenance. Common in commercial, less so in multifamily. |
Frequently Asked Questions
How much money do I need to start investing in multifamily?
It depends on the strategy. House hacking a duplex with an FHA loan can be done with as little as 3.5% down. A small apartment building (5–20 units) typically requires 20–30% down plus closing costs and reserves. Syndication as a GP requires minimal personal capital — your contribution is your time and deal-finding ability. There are legitimate paths into multifamily for investors at almost every capital level.
Is multifamily investing risky for beginners?
All investment involves risk, but multifamily mitigates many of the risks that plague single-family investors. Multiple income streams protect against total vacancy, income-based valuation removes dependence on market comps, and professional management systems reduce operational risk. Proper education, deal analysis, and mentorship dramatically reduce beginner risk.
How long does it take to get your first multifamily deal?
Most investors in a structured program close their first deal within 6–18 months of getting serious. The timeline depends on your market, your financing readiness, how much time you invest weekly, and whether you have guidance. Having a mentor or a community significantly compresses this timeline.
What is the best market for multifamily investing?
There’s no single best market, it depends on your goals. Sunbelt markets (Texas, Florida, Georgia, Arizona, Tennessee) have historically offered strong rent growth, population inflows, and landlord-friendly laws. However, secondary and tertiary markets often offer better cap rates with less competition. The right market is one you’ve analyzed deeply and understand.
Can I invest in multifamily from out of state?
Absolutely. Many of the most successful multifamily investors operate nationally. The key is building a local team in your target market: a broker, property manager, lender, attorney, and inspector. With a strong team in place, geography becomes less of a barrier.
What is the difference between multifamily investing and real estate syndication?
Multifamily investing is the broad strategy of owning apartment properties. Syndication is a specific structure for acquiring larger properties by pooling capital from multiple investors. You can invest in multifamily without syndication (buying directly with your own capital), or you can use syndication to buy deals you couldn’t afford alone.
How do I find a good multifamily mentor?
Look for someone who is actively investing, not just teaching theory. Check their track record (student outcomes, personal portfolio), look for a structured curriculum, peer community, and ongoing deal support. Avoid programs that charge high fees for vague “access.” Rod Khleif’s Warrior Program is consistently rated one of the top multifamily mentorship programs in the country, with verified student-owned doors as evidence.
What are the tax benefits of multifamily investing?
Multifamily investing offers some of the most favorable tax treatment of any asset class. Key benefits include depreciation (reducing taxable income without a cash expense), cost segregation studies (accelerated depreciation on components), 1031 exchanges (defer capital gains taxes indefinitely), and mortgage interest deductions. Many multifamily investors pay significantly lower effective tax rates than W-2 employees.
Source: Rod Khleif


 Accessibility